Quick answer
A performance car is financed like any other car, usually with a secured car loan if the car meets the lender's age and type rules, or a personal loan if it doesn't. The difference is the running costs: insurance, premium fuel, tyres and brakes cost more. Budget for those first, check modifications with your insurer, and compare loans on total cost.
Key points
- Performance cars are financed like other cars, subject to the lender's rules.
- Insurance, fuel, tyres and brakes usually cost more than on an everyday car.
- Declare every modification to your insurer before you drive.
- Track use is often excluded from standard insurance policies.
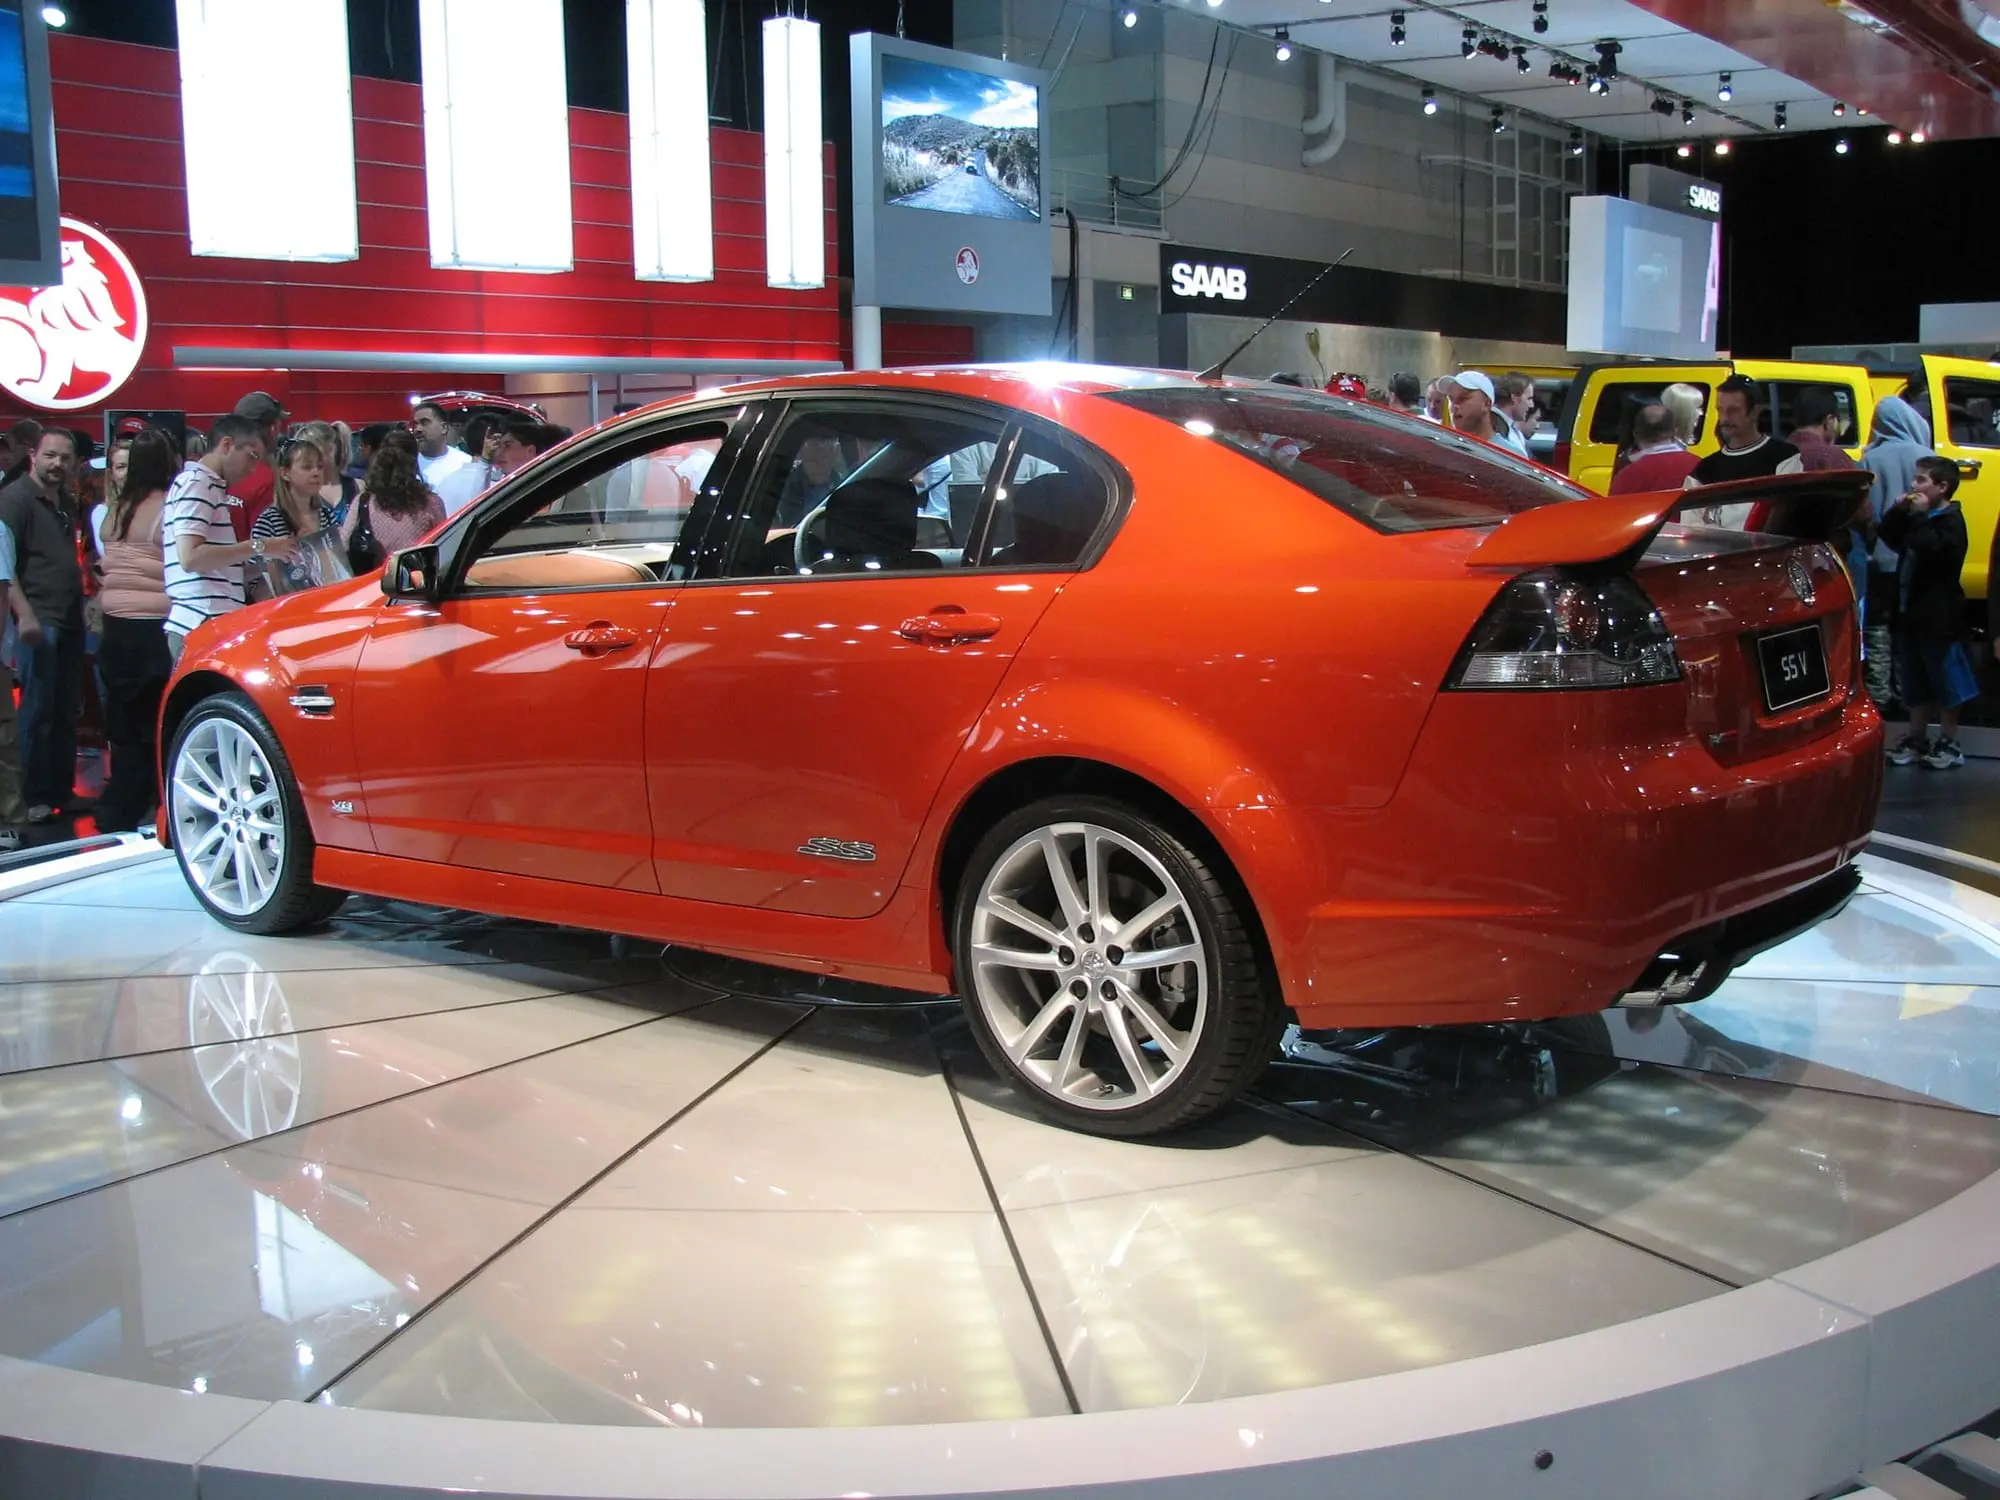
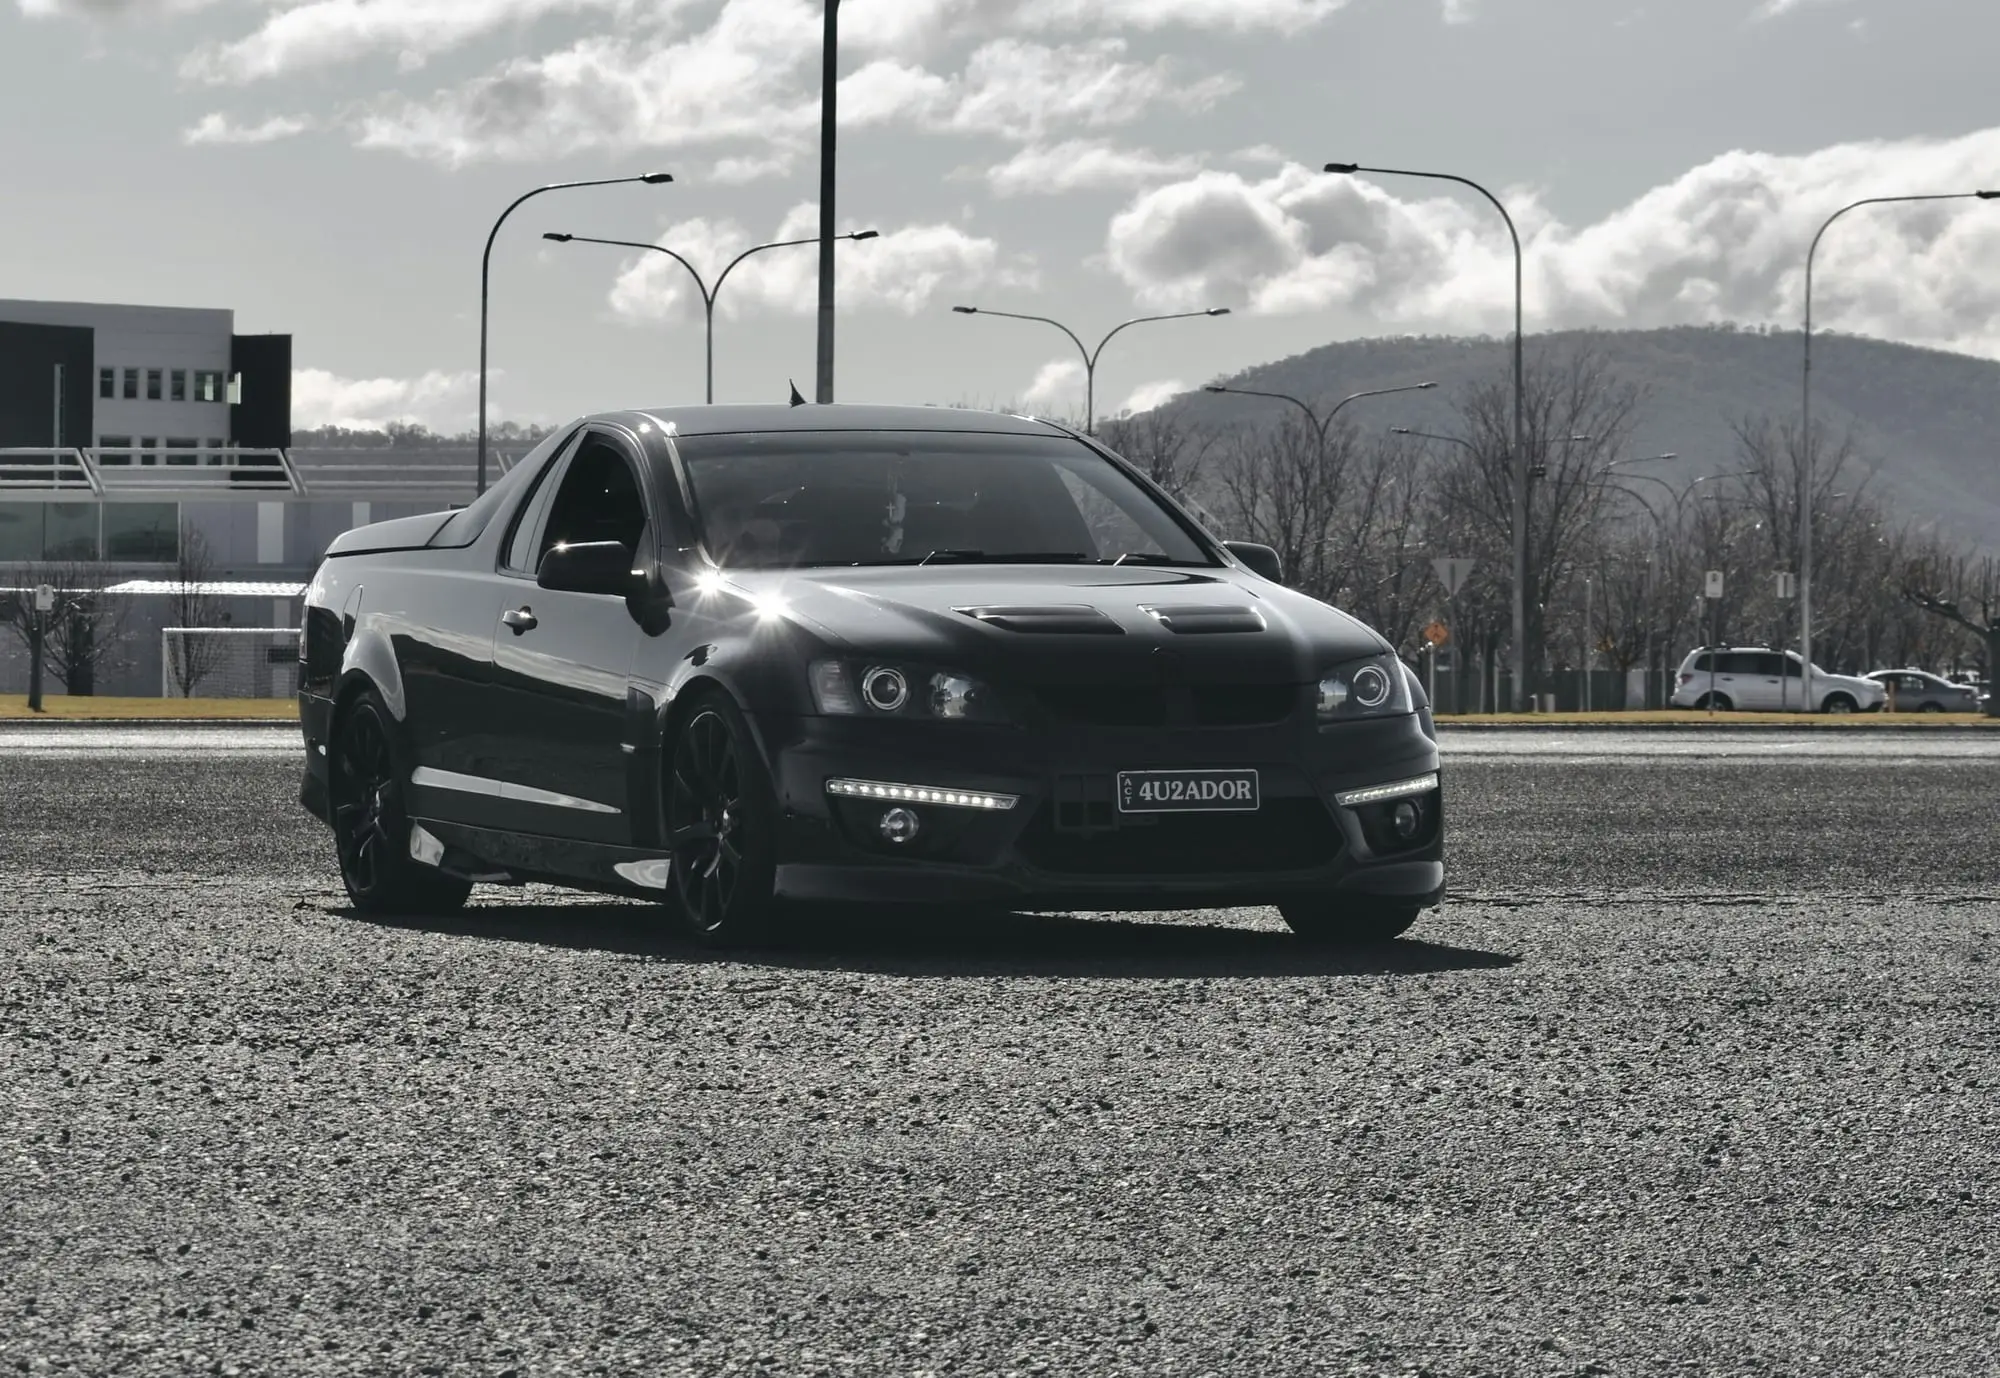
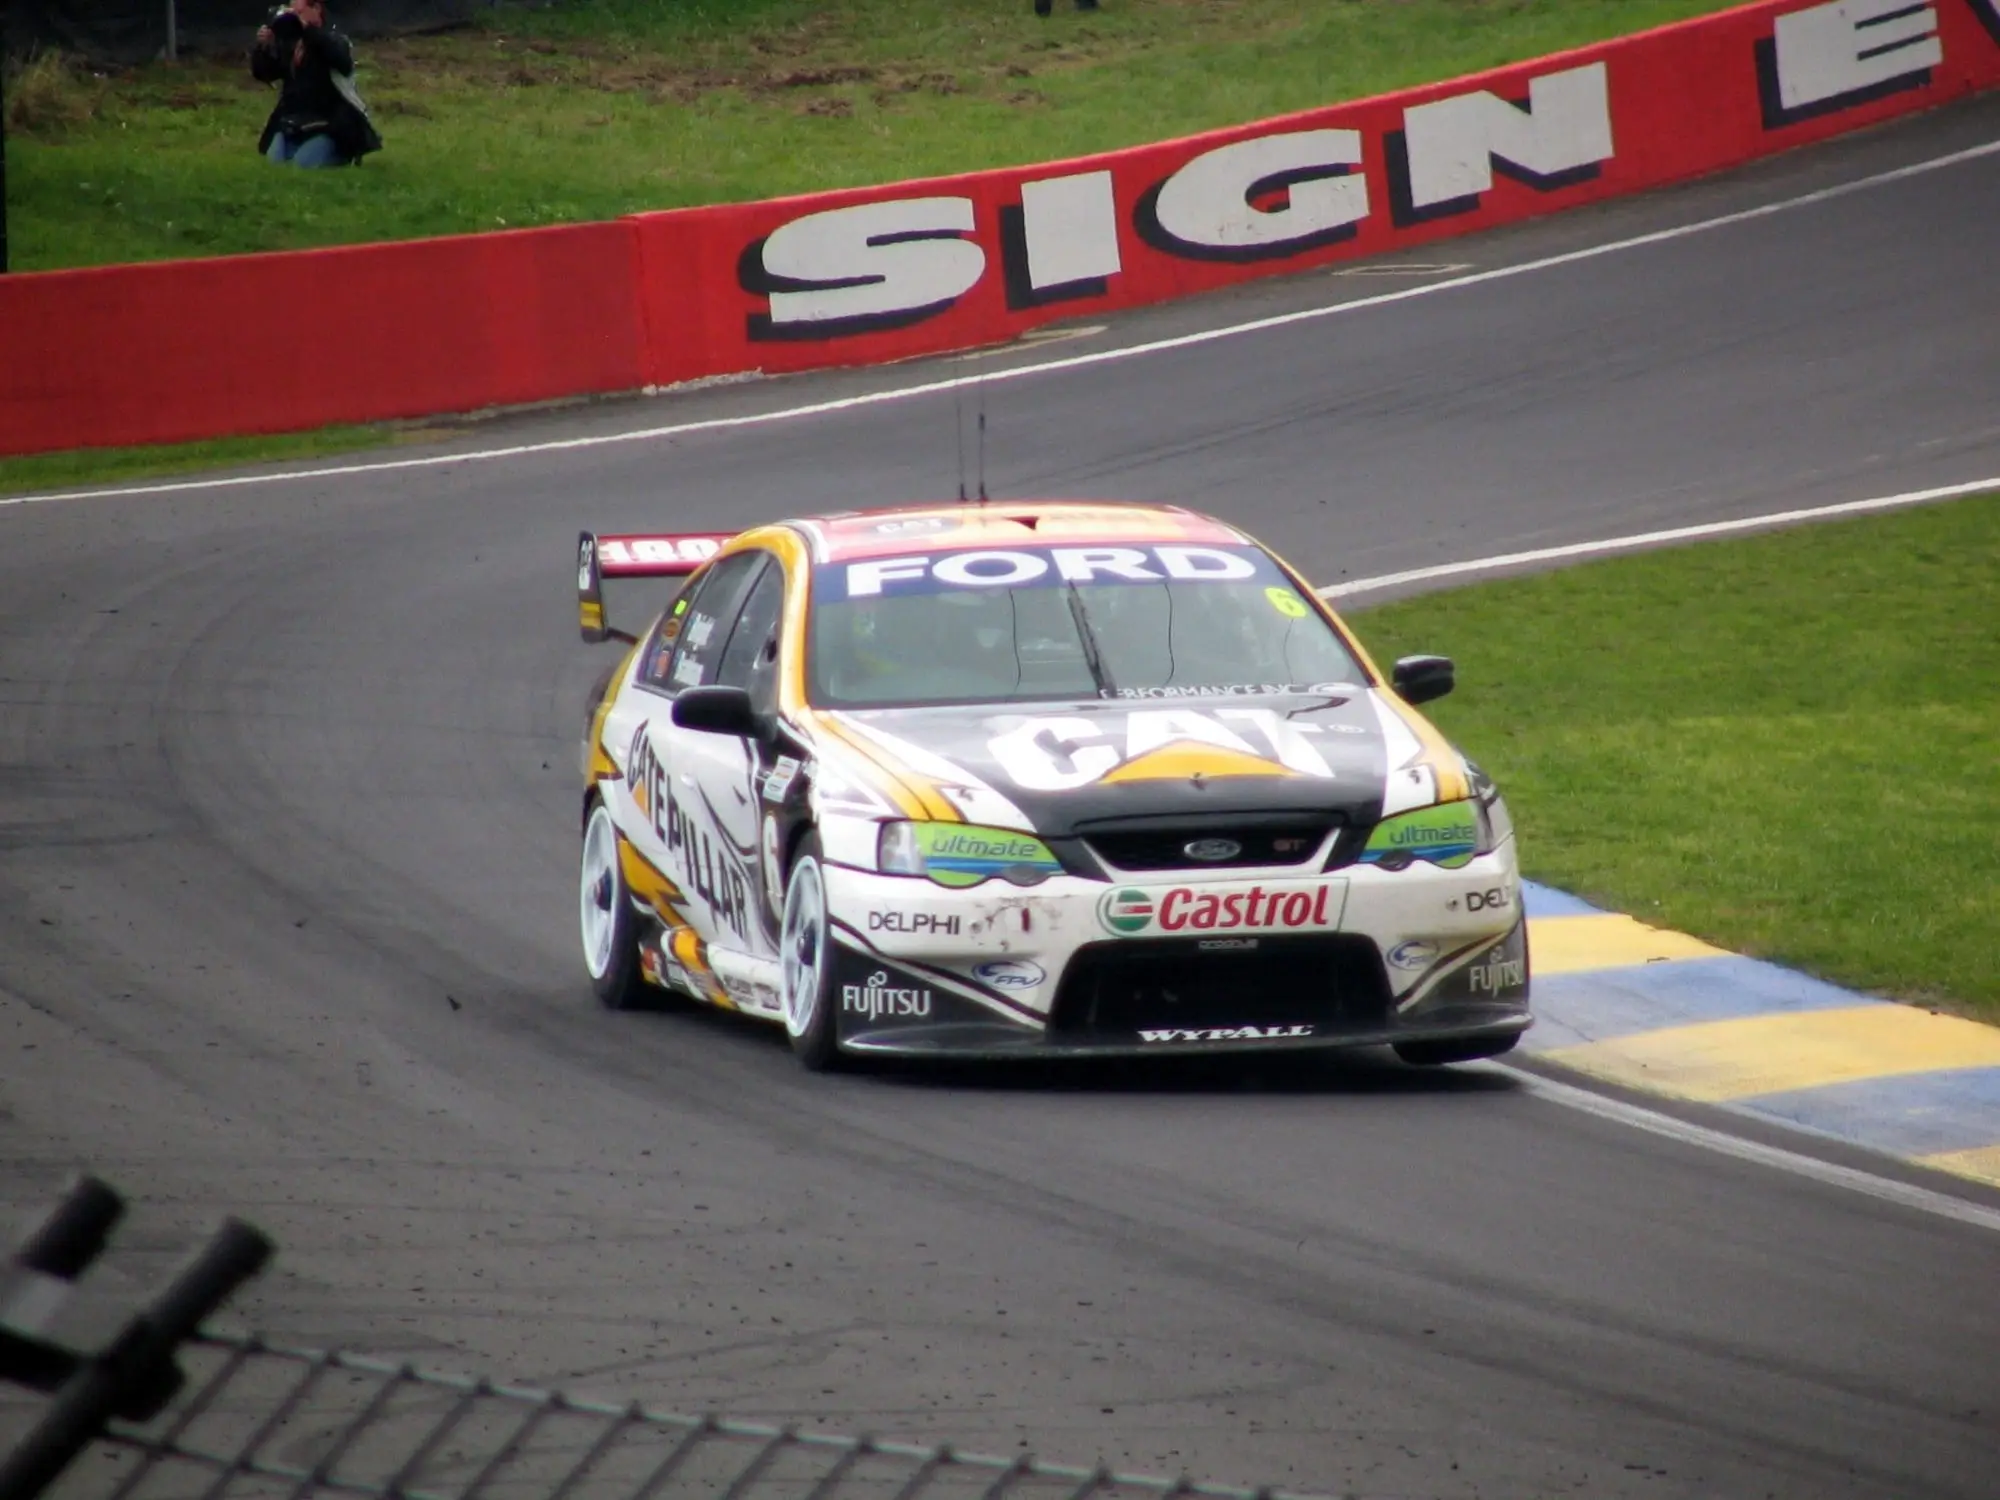
Every year, half the country stops to watch the Great Race charge up Mountain Straight at Bathurst. That love of a big engine and a loud exhaust runs deep in Australian car culture. It’s why clean SS Commodores, XR8 and FPV Falcons, HSV Clubsports and Maloos still draw a crowd at every car show, and why so many people dream of owning one.
Since Ford and Holden stopped building cars here, the last of the locally made V8s have become prized by enthusiasts. Imported performance cars have filled the gap. Either way, financing a car built for fun needs a slightly different budget from financing a commuter.
How do you finance a performance car?
The loan itself is no different from any other car loan. The two main routes are:
- A secured car loan. The car is the security, which usually means a lower cost. The lender will have rules on the car’s age, type and value, and may ask about modifications.
- An unsecured personal loan. Useful when the car is older than a secured lender allows, heavily modified or a project. The car stays free of the lender’s interest, but the loan usually costs more.
If you’re chasing an older muscle car, our classic car loans page covers how lenders treat older vehicles. If it’s a late-model car from a dealer, read new car loans and dealer finance vs a car loan before you sit down in the finance office.
What does a performance car really cost to run?
This is where performance-car budgets come unstuck. The weekly repayment might look fine, but the car keeps asking for more.
| Cost | What tends to change with a performance car |
|---|---|
| Insurance | Higher-powered cars usually cost more to insure, especially for younger drivers or in some postcodes |
| Fuel | Bigger engines drink more, and many need premium unleaded |
| Tyres | Wide, low-profile performance tyres cost more and can wear quickly |
| Brakes | Larger brake packages mean pricier pads and rotors |
| Servicing | Specialist servicing and higher-spec fluids add up |
| Stamp duty and taxes | Duty depends on your state and the price; luxury car tax may already be built into the price of dearer cars |
Moneysmart’s car advice is blunt that running costs may be more than you expect. With a V8 that’s doubly true. Put honest figures into the car budget planner, especially for insurance and fuel. Get a real insurance quote on the exact car before you commit, because it can change the whole picture.
How do modifications affect the loan and insurance?
Plenty of performance cars come with a few mods: an exhaust, a tune, coilovers, bigger wheels. Some are fine; some cause headaches.
- Insurance. Insurers generally need to know about modifications. Undisclosed mods can put a claim at risk.
- Roadworthiness. Some modifications need engineering approval in your state before the car is road-legal.
- The lender. If the car secures the loan, the lender has an interest in its value and may have conditions about changes. Check your loan terms before you start modifying.
- Resale. Original, well-documented cars often sell more easily than heavily modified ones.
If you’re buying a modified car, ask for receipts and any engineering certificates, and have it inspected by someone who knows the model.
Should you use a balloon payment?
Balloon (residual) payments are common in performance-car finance because they make an expensive car’s regular repayment look smaller. The catch is the lump sum at the end, and that the total you repay is usually higher. If you choose one, have a realistic plan for paying it: savings, selling the car, or refinancing, with the understanding that refinancing isn’t guaranteed. Our refinancing page explains what’s involved.
When you’re comfortable with the numbers, you can see your performance car loan options before committing to anything.
Is a performance car a smart first car?
For younger drivers, insurance on a powerful car can cost as much as the loan repayments, and some states restrict which vehicles provisional licence holders can drive. Check your state’s rules on high-powered vehicles for P-platers, get an insurance quote and run the budget first. A quicker hatch or a warm sedan might be the smarter stepping stone, with the V8 as the next goal.
Ready to hear it start up in your driveway?
Plan the whole cost first: the loan, the insurance, the premium fuel and the tyres. If the comfortable repayment from your budget still covers it with room to spare, start an application with our secure partner and see your options before you commit. A real person can help if you’re weighing up a balloon or a personal loan for an older car. Please give accurate figures for income and existing repayments so your options reflect what you can genuinely afford.
Frequently asked questions
Can I get a car loan for a V8 or performance car?
Yes. Performance cars are financed with the same kinds of loans as other cars. A secured car loan is common if the car meets the lender's rules on age and type; older or heavily modified cars are often financed with a personal loan instead.
Will insurance affect my loan?
If the car secures the loan, the lender may require comprehensive insurance. Performance cars can be expensive to insure, especially for younger drivers, so get an insurance quote before you sign and include it in your budget.
Do modifications matter to the lender?
They can. Modifications may affect insurance, roadworthiness and resale value, and some lenders have conditions about changes to a car that secures the loan. Tell your insurer about every modification and keep the paperwork.
Should I take a balloon payment to keep repayments down?
A balloon lowers the regular repayment but leaves a large lump sum at the end and usually raises the total you repay. Only consider it if you have a clear, realistic plan for paying it.
Can I finance a car I'll use on track days?
You can finance a road-registered car you sometimes take to a track day, but many standard insurance policies don't cover track use. Check your policy, and consider separate cover for events.